


Opening View
This week’s useful earnings signal is not simply whether profits are rising. It is whether the assets supporting those profits can produce cash when obligations fall due.
Transcorp Hotels reported N15.54 billion of profit after tax for the nine months to September, up from N14.82 billion a year earlier. Yet operating activities consumed N15.93 billion of cash. That divergence makes the results more than a hospitality-demand story.
The investment question is who owes the company money, when those balances become cash, and how that timetable compares with its borrowing commitments. A higher profit figure cannot answer those questions. Equally, a cash outflow alone does not establish distress: its causes, recoverability and financing matter.
For the week ahead, our emphasis is on separating operating performance from financing effects. Investors should apply that distinction to new company results, while using today’s government bond auction to establish the return available without taking company-specific earnings risk. The decision is not equities versus bonds in the abstract. It is whether a particular equity offers sufficient compensation for its additional cash-flow uncertainty.
The Big Picture:
Transcorp Hotels’ accounts report N42.72 billion of net related-party receivables and N4.19 billion of interest income on intercompany loans. Our interpretation: shareholders are assessing credit exposure within the wider corporate group alongside the hotel operation. They should distinguish the value of the operating business from the recoverability of those financial claims, avoiding double-counting the claims and their future income.
That is a valuation discipline, not an allegation of default or improper conduct. Documented repayments, stronger operating cash generation and lower borrowing would materially improve the assessment.
Nigeria Market Intelligence
The financing burden deserves its own analysis. Transcorp Hotels’ borrowings reached N54.96 billion at September-end, against N10.52 billion at December-end. Higher finance income helped offset rising finance costs; lower tax also supported profit after tax. Watch cash collections and debt reduction, rather than treating reported profit growth as a sufficient entry signal.
Today’s bond auction will establish actual entry economics. The DMO is offering N1.75 trillion across reopened bonds, calculated from its three offer amounts. Nigeria’s annual inflation eased to 14.63% in September, according to reported NBS figures, but disinflation does not establish an attractive purchase price. Watch clearing yields and Wednesday’s settlement before extrapolating a bond rally.
Use dated market levels, not a broad recovery narrative. The NGX All-Share Index closed Friday at 247,539.73; the official NFEM exchange rate was N1,332.26 per US dollar. Neither establishes an investable equity bargain or an executable FX rate. Watch participation around company results and the actual conversion terms available to businesses.
Global Market Intelligence:
AI’s funding question has moved into credit markets. Reuters reported selling in both CoreWeave shares and bonds on Friday as investors questioned debt-funded expansion. For Nigerian issuers, the relevant channel is potential tightening in external financing appetite, not a claimed direct contagion. Watch financing terms and cash-generation guidance through earnings season.
China’s growth release is already out. GDP expanded 4.5% year on year in the third quarter, compared with 4.3% in the second. This supports the global demand backdrop, but an uneven, export-supported recovery is not proof of a broad commodity upswing. Watch whether domestic demand strengthens before lifting Nigerian commodity-revenue assumptions.
Dollar funding still faces an inflation constraint. US annual CPI inflation reached 3.7% in September. Nigeria’s softer inflation therefore does not automatically translate into cheaper dollar borrowing. Watch Treasury pricing and credit spreads separately; the next Fed meeting is 27–28 October, next week.
Delivered energy costs can lag futures. Reuters’ Monday Asian-session report highlighted high shipping and insurance costs for physical oil delivery. Even a drop in Brent futures may not quickly lower a Nigerian business’s landed energy bill. Watch freight and supplier quotes before revising margins.
Asset Class Implications:
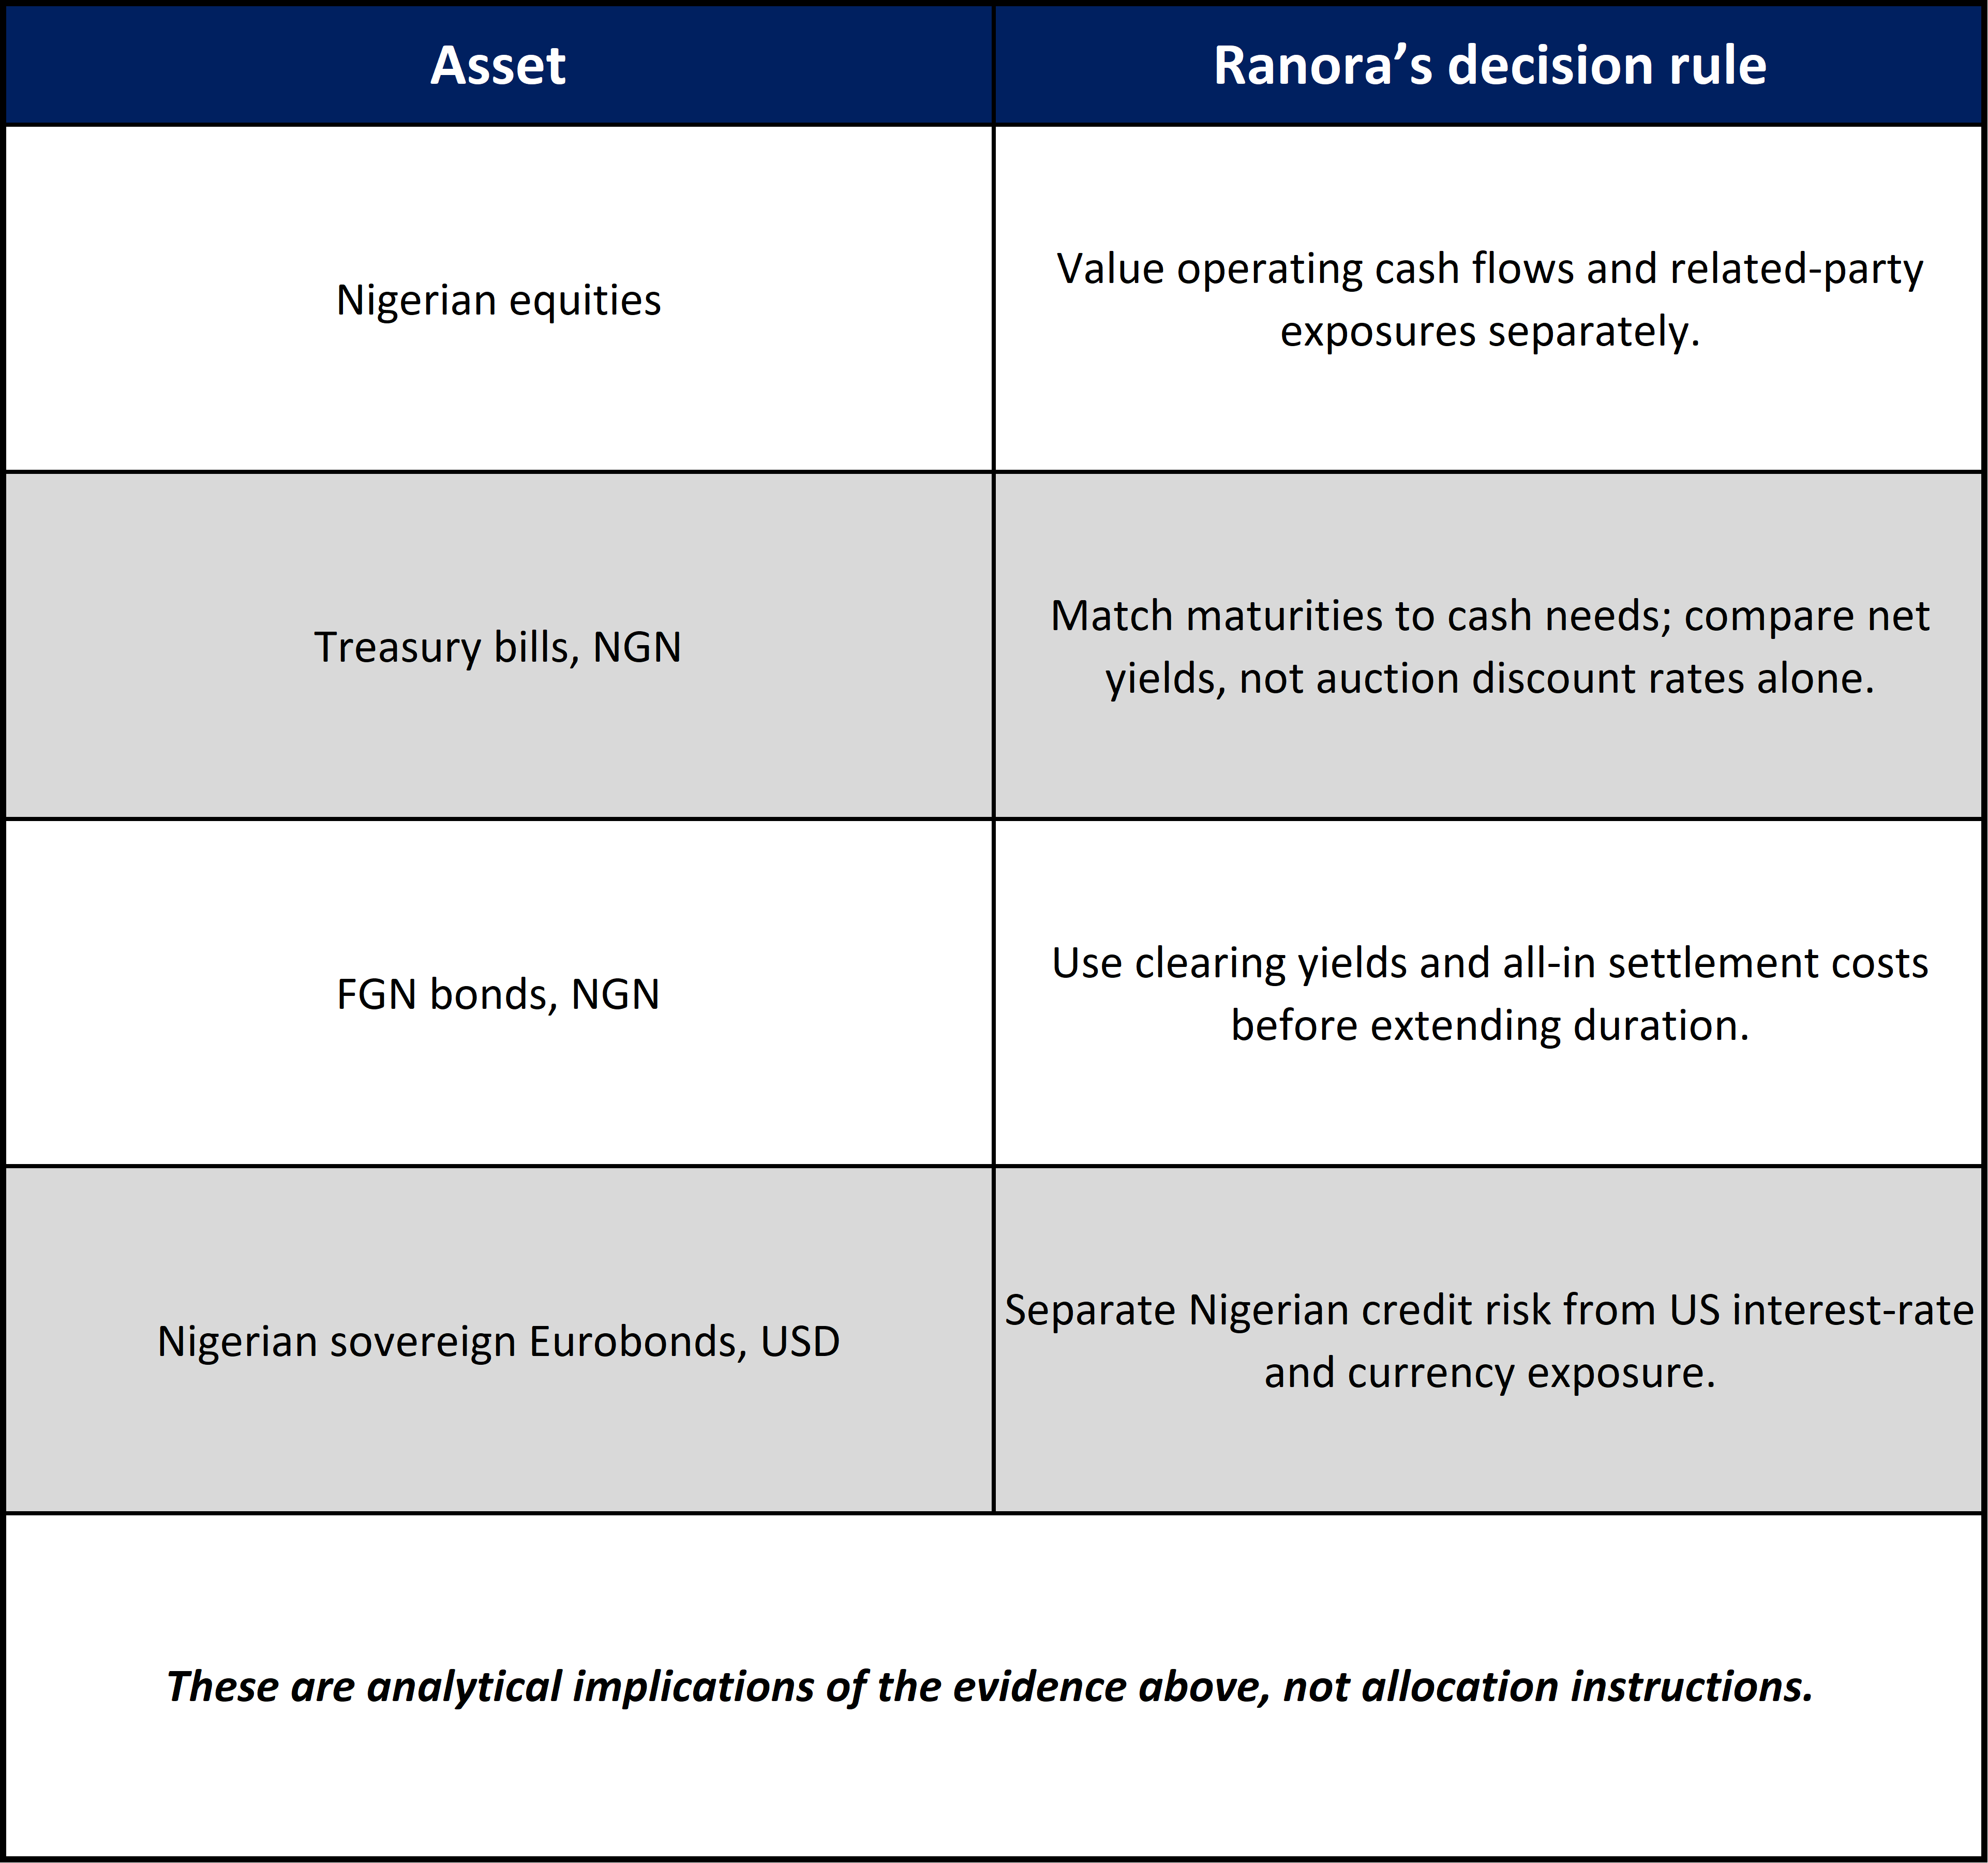
Investment Ideas for the Week:
These are long-only, unleveraged research candidates, not executed positions. No unconditional entry is supported before the checks below are completed.
Transcorp Hotels ordinary shares, NGN. Thesis ID:
NG-EQ-TRANSCOHOT-CASH-20261019. Defer entry. GTI’s 16 October closing reference is N290.50, not a dealing offer. The catalyst would be evidence that related-party collections and operating cash generation reduce funding dependence over the next two reporting periods. A prospective investment needs a multi-year horizon. Valuation should separate sustainable hotel earnings from recoverable financial claims; profit growth alone does not establish cheapness. Principal risks are delayed collections, higher finance costs and limited exit liquidity. Reconsider after verified collections, a defensible valuation and live market depth. Current brokerage costs, statutory charges and investor-specific tax treatment are unverified. No dividend entitlement is assumed; corporate-action eligibility must be checked before any later entry.19.00% FGN FEB 2034, NGN. Thesis ID:
NG-FGN-2034-INCOME-20261019. Conditional post-auction candidate. Today’s auction is the catalyst; its result is not yet available at this edition’s cutoff. The rationale is to compare contractual naira income with taking uncertain corporate cash-flow risk, preferably against a liability horizon extending to February 2034. The 19% figure is the coupon, not today’s yield. Compare the resulting net yield with shorter FGN maturities and bills before accepting longer duration. Inflation, rising yields, sovereign credit and early-sale liquidity remain risks. The DMO specifies a N50,001,000 auction minimum and accrued interest in addition to price. Dealer fees, secondary-market spreads and applicable taxes must still be confirmed. Defer if the net premium is inadequate or the holding period is too short.Nigeria 6.125% SEP 2028 sovereign Eurobond, USD. Thesis ID:
NG-USD-2028-CARRY-20261019. Defer pending a fresh quote. The DMO’s 15 October closing reference, published 16 October, reports a 6.196% yield, distinct from the coupon. Its shorter maturity makes it a candidate for comparing USD income through September 2028 with longer Nigerian dollar bonds. The catalyst is an executable quote offering adequate credit compensation against a maturity-matched US Treasury, not merely falling US yields. No verified current spread establishes mispricing. Sovereign default, duration, liquidity and currency risks remain; naira strength can reduce naira-translated returns. Obtain bid/offer spreads, accrued interest, custody charges, minimum lot, FX conversion costs and tax applicability before assessing net economics. The published price convention is insufficiently clear to treat it as an all-in settlement amount. S
Ranora View:
Do not pay an earnings-growth valuation for income whose cash recovery has not been assessed. Our preference this week is to make equity additions conditional on collection evidence and a valuation that compensates for financing risk, while evaluating sovereign income on actual entry terms. This is not a blanket rejection of Transcorp Hotels or a claim that bonds are risk-free. The investment case improves with repayments and self-funded operations; it weakens with growing receivables and continued borrowing dependence.
Conclusion: Ranora analysis.
What to Watch Next:
Monday, 19 October: DMO clearing yields and allotment by bond, not headline demand alone.
Wednesday, 21 October: Auction settlement and the subsequent secondary-market response.
Through the week: New company filings, particularly collections, related-party balances and debt-service commitments.
Ahead of the 27–28 October Fed meeting: US Treasury pricing and Nigerian Eurobond spreads as separate signals.
Question of the day:
What evidence would persuade you to pay for profit growth when operating cash flow is moving in the opposite direction?
Stay smart. Stay informed. Subscribe to Ranora Market Outlook for free and support independent market analysis.